UK CBAM
UK CARBON BORDER ADJUSTMENT MECHANISM
From imported goods and verified emissions data to UK CBAM liability.
From 1 January 2027, certain carbon-intensive goods imported into the UK will become subject to UK CBAM.
CBAM Advisory helps UK importers and overseas producers understand which goods are affected, establish the required embodied-emissions information, prepare verified actual emissions where appropriate, assess carbon price relief, and support the information needed for UK CBAM returns.
UK CBAM CURRENT POSITION
Starts
1 January 2027
Initial sectors
Aluminium · Cement · Fertiliser · Hydrogen · Iron & Steel
Registration threshold
£50,000 of CBAM goods, subject to the applicable registration rules.
Emissions at launch
Direct embodied emissions
Indirect Emissions
Not included at implementation; government has said inclusion is delayed until at least 2029.
WHO DOES UK CBAM AFFECT?
UK Importers
You may need to determine whether imported goods are within scope, monitor the £50,000 registration threshold, register for UK CBAM, obtain emissions information, calculate liability, claim eligible carbon price relief and submit CBAM returns.
Overseas Producers
Your UK customer may ask you for emissions-intensity information and verification evidence so that actual emissions can be used instead of UK default values.
HOW UK CBAM LIABILITY IS BUILT
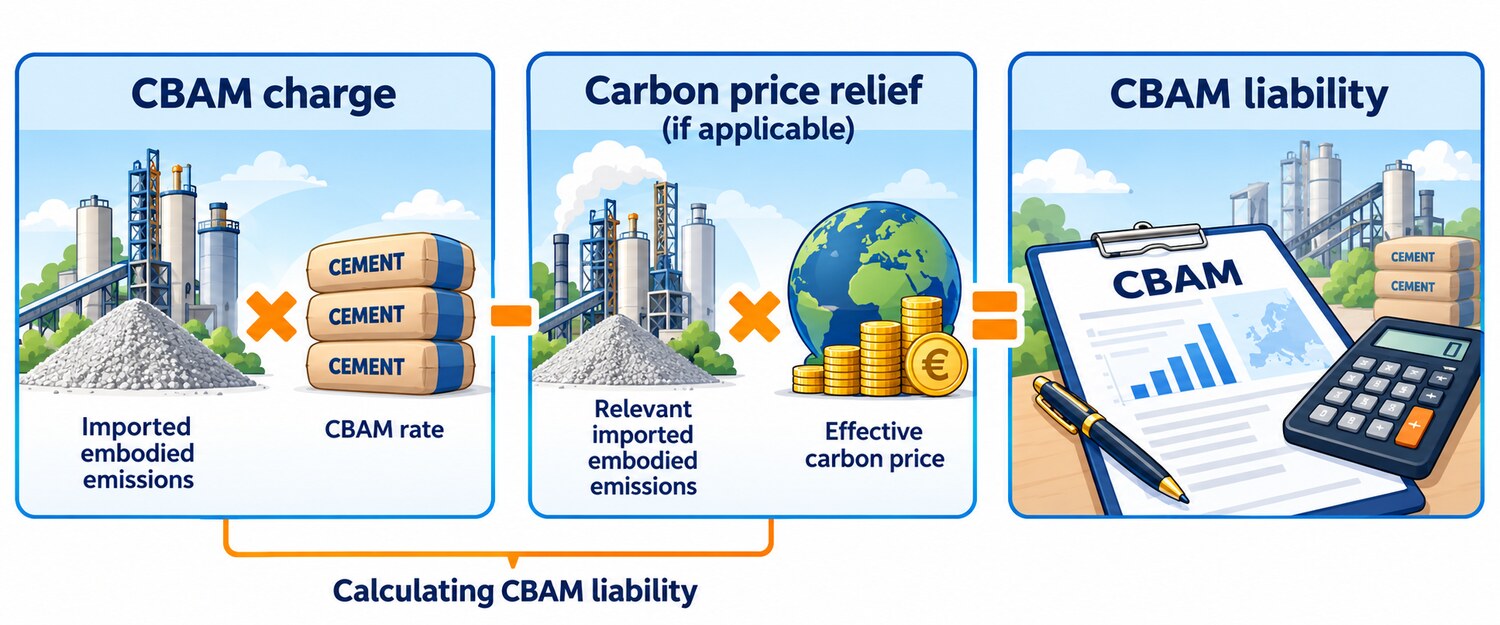
UK policy requires the imported weight and emissions intensity to determine embodied emissions, while qualifying overseas carbon pricing can reduce the liability through Carbon Price Relief.
ACTUAL EMISSIONS OR DEFAULT VALUES?
Actual emissions
Where actual emissions are used, the liable person needs verified emissions-intensity data from the producer.
The producing installation appoints the appropriate verifier, and the UK importer must retain the relevant verification report or verification summary.
Default emissions values
Where actual data are unavailable, or appropriate verification evidence is not available, UK default emissions values can be used.
The UK framework also allows defaults to be used for relevant precursor goods in certain circumstances.
CBAM Advisory helps determine which data route is practical and what evidence is needed to support it.
FOR OVERSEAS PRODUCERS: WHAT WILL YOUR UK CUSTOMER NEED?
- Producing installation
- CBAM good and commodity code
- Production process
- Applicable system boundary
- Production quantity / functional unit
- Fuel and material consumption
- Direct process and combustion emissions
- Relevant precursor information
- Emissions intensity
- Verification evidence
- Applicable overseas carbon-pricing information
The UK has already published a System Boundaries Document specifically for determining direct emissions embodied in CBAM goods.
CARBON PRICE RELIEF
Has carbon already been priced in the country of production?
UK CBAM allows the liable person to claim Carbon Price Relief (CPR) where relevant embodied emissions have been subject to a qualifying carbon pricing scheme and the required evidence is available.
The calculation can involve:
The UK rules require a prescribed carbon pricing verification form and supporting verified information for the claim.
WHAT CBAM ADVISORY CAN SUPPORT
- UK CBAM applicability and commodity-code assessment
- £50,000 registration-threshold assessment
- UK CBAM system-boundary assessment
- Actual embodied-emissions calculation
- Relevant precursor assessment
- Default-value assessment
- Verification-readiness support
- Verifier coordination
- Carbon Price Relief documentation
- Carbon-pricing verification support
- Importer / overseas producer data coordination
- UK CBAM liability calculations
- Return-readiness review
SHORT COMPLIANCE TIMELINE
- 1 January 2027 — UK CBAM begins.
- 1 January–31 December 2027 — First accounting period.
- 31 May 2028 — First UK CBAM return and payment deadline.
- From 2028 — Accounting periods move to a quarterly cycle.
Will your goods be imported into the UK from 1 January 2027?
Send us your:
We can identify whether UK CBAM applies, what emissions information will be required and what should be prepared before the first imports take place.